


What the map reveals about new pipeline interconnect pace
For an Australian energy professional watching United States shale development from a desk in Brisbane or Perth, the pace at which new pipeline interconnects come online can feel abstract. Yet each lateral tap, regulator station, and metering skid across Texas, Pennsylvania, and North Dakota quietly reshapes how gas reaches market and how acreage value drifts across the continent. Mapping platforms that visualise these hooks in near-real time have become the analyst's working bench, turning a sprawling infrastructure question into a layer a person can read in minutes. When a Sydney-based funds manager asks whether to back a mineral acquisition in the Haynesville or the Marcellus, the answer often starts with what the map is showing that month.
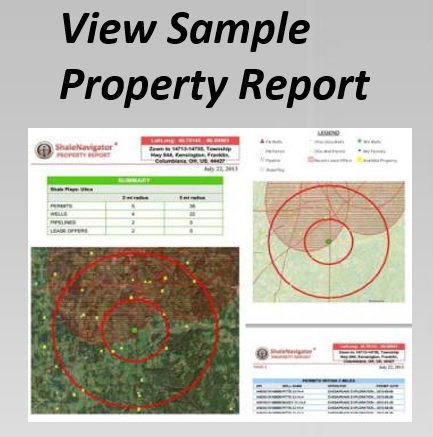
Shale Navigator has built its application around exactly this kind of reading. The platform pulls drilling permits, lease offers, gathering lines, transmission corridors, and active interconnect projects into a single workspace, so the relationship between upstream activity and downstream capacity is no longer a matter of piecing together regional PDFs. For Australian subscribers, who routinely balance exposure to projects 14,000 kilometres away with the volatility of the domestic LNG market, that consolidated view becomes a useful edge. Pipeline interconnects in particular reveal the bridge between wellhead production and firm takeaway, and reading them well can save a deal that looked attractive six months earlier.
The discussion below walks through the signals worth watching, the layers that translate those signals into meaning, and the practical steps an Australian investor can take to turn those readings into a decision. It also touches on why timing matters more in some basins than in others, and where Australian energy portfolios tend to align with US plays.
Reading permit density as the earliest hint of new capacity
Permit filings on the platform appear as small dots clustered along township and range lines, and they are usually the first measurable sign that a new gathering system or interconnect is on the drawing board. Operators rarely publish a formal pipeline announcement months before the survey crews go out; instead, the pattern emerges silently through the Application for Permit to Drill cadence. A basin that suddenly shifts from one permit per two square miles to three or four across the same window often presages a new compressor station, a tap on an existing mainline, or a complete greenfield loop. For a Santos or Woodside analyst used to watching Gladstone feedgas curves, the rhythm of US permits reads in a familiar way.
Deeper patterns matter as much as raw counts. When the dot density hugs a single east-west corridor that already carries a transmission line, the implication is usually a series of taps rather than a full new build, and that means faster connection timelines, often inside a single season. By contrast, permits scattered in an unconnected quadrant of the map suggest an operator is preparing the resource base for a future mainline extension, which is a longer-cycle trade. The map's heat-map weighting makes this distinction visible without much additional clicking.
The pace question becomes genuinely readable when permit density is layered against published project pages from major midstream operators. A sudden wave in Reeves County with no corresponding Kinder Morgan or Energy Transfer announcement for another year usually means a private operator is laying groundwork, and that is where Melbourne-based mineral-rights investors often find the early-money position. Catching that wave a quarter ahead of the formal interconnect notice is one of the cleanest payoffs of using mapping software instead of waiting on press releases.
Spotting lease offer clusters beside proposed routes
Lease offer overlays on the platform are perhaps the most underrated indicator of coming pipeline activity. When a lessor drops a fresh package of mineral-rights offerings in a band that aligns suspiciously well with an announced or hinted pipeline corridor, the inference is straightforward: they expect a buyer who will price acreage according to forthcoming takeaway. Landmen and mineral buyers operating out of Parramatta or Adelaide have learned to flag these offers the same week they appear, because a large corporate land department is usually bidding against them within days.
The Shale Navigator interface lets a subscriber draw a one-mile buffer around any proposed pipeline geometry and instantly see which lease offers fall inside. Used alongside a county-by-county search for individual holdings, the technique helps narrow a watchlist from hundreds of parcels to a dozen with genuine proximity to a future interconnect. Investors who pair this view with the platform's parcel-level ownership data, often covered in guides such as locating trust-owned leases efficiently, are typically the first to spot when a single family trust has been quietly assembling a corridor position. That trust is frequently the seller once the interconnect is greenlit, which makes the buffer exercise a quiet source of leads.
Reading lease offer clusters also helps avoid the trap of chasing acreage already locked up by long-term dedications. If the buffer is dense with offers but the surrounding parcels are blank, the operator of a planned system has likely already secured its anchor dedications and is filling gaps. For Australian watchers, this is functionally similar to watching the Karratha LNG precinct or the Surat Basin's lease calendars, where the same auction-then-fill pattern repeats project after project.
Tracking existing pipeline proximity and branch logic
Existing pipeline layers do not announce new interconnects, but they explain why some new ones appear and others do not. Shale Navigator's transmission layer shows diameters, operating pressures, and approximate available capacity drawn from public tariffs, which together make the parent-child relationship between a mainline and a prospective lateral almost self-evident. A 36-inch high-pressure header running east-west will attract tap requests wherever it crosses a producing county; a 20-inch line at low pressure does not.
The platform's branch-logic view, layered over permit dots and lease offers, lets a subscriber test a simple question: what is the shortest credible path from this producing block to a header with spare room? A map that returns a tidy two-mile answer points to an interconnect that may already be in survey. A map that returns a circuitous 30-mile routing across multiple landowners points to a project that will sit in permitting for years. For Australian investors comparing US opportunities against a domestic AEMO outlook or against LNG netback curves into Asia, the shortest-path analysis offers a grounding check that headlines rarely provide.
This same logic also reveals when an interconnect is built but underutilised, which can matter as much as a brand-new build. A tap that opened during the last gas-price spike may sit at minimal flow today, and the platform's older permit history alongside current production dots will usually show the steep decay. That kind of context is what stops a Sydney or Perth funds manager from pricing in a phantom takeaway premium that disappeared two winters ago.
Comparing pace changes across basins and over time
The most honest answer to the question of pace is rarely a single number; it is a comparison. The platform's time-slider tools make it straightforward to replay the same map at six-month intervals and observe how quickly the cluster of new interconnects has thickened in one basin versus another. A subscriber watching from the Brisbane CBD can flip between the Haynesville in 2021, 2023, and today, and watch the interconnect density catch up to the Marcellus's earlier build-out. The same exercise over the DJ Basin or the Anadarko shows the long tail of midstream investment that keeps acreage competitive years after the rig count has moved on.
Cross-regional comparison is where Australian subscribers tend to find their most useful framing. The Pilbara LNG precinct and the Surat-to-Gladstone pipeline corridor both illustrate how a producing region can stay highly active in drilling while still needing fresh takeaway every few years. Watching pace changes for a US play that resembles one of those Australian systems helps an analyst judge whether the current US pipeline build is leading, lagging, or running in step with the rig count. That judgement then feeds back into the timing of any mineral acquisition made through the platform's subscription layers.
Using storage context to time interconnects against demand cycles
One of the subtler links the platform supports is between storage levels in adjacent regions and the speed at which new interconnects actually flow. Producers hesitate to push gas onto a saturated network, and midstream operators delay commercial in-service dates when storage is at seasonal highs. The interpretive piece on gas storage drilling timing walks through this dynamic in more detail, and it is worth pairing that reading with a live map session. Storage layers on Shale Navigator show how full nearby salt caverns and aquifer reservoirs are at any given week, and that single overlay often explains why a pipeline that has been months from completion for two quarters is suddenly operational.
For Australian subscribers, this storage lens reads very naturally. Domestic gas storage is comparatively limited in eastern Australia, which is why winter peaks and summer lulls shape producer behaviour so visibly. The same principle, scaled up under the Appalachian salt stratum or along the Louisiana Gulf, plays out at a different magnitude but with similar timing logic. Subscribers who bring that intuition across the Pacific tend to anticipate US interconnect in-service dates more accurately than those who do not.
Signs on the map that a new interconnect is imminent
- Permit density jumps inside a one-mile strip along an existing transmission header
- Lease offer packages appear in a linear pattern that mirrors a public survey corridor
- Compressor-station icons are added within sight of producing pads
- Gathering-line layers are extended onto the platform even before a tariff filing
- Multiple operators file permits in the same township within a sixty-day window
Practical steps for an Australian subscriber evaluating a deal
- Set a saved map view for each US basin of interest and revisit it monthly to track interconnect pace changes
- Draw a buffer around proposed pipelines and cross-reference it with lease offers and ownership records before bidding
- Compare current permit density against the same quarter two years earlier to gauge whether build-out is leading or lagging drilling
- Open the storage layer alongside permits to time entries ahead of expected commercial in-service dates
- Use the platform's notification tools to alert a desk in Sydney or Perth whenever a specific operator files permits in a watchlist county
A live map beats a press release by a season, and in the gas business a season is sometimes all the margin a deal needs. Open a free seven-day Shale Navigator account, drop a few watchlist counties onto the workspace, and read the pace of new interconnects the way the operators themselves read it: one permit dot at a time.